
Legal Questions to Ask Before an Online Real Estate Closing
Remote closings still carry full legal weight. Ask these legal questions before an online real estate closing to protect your purchase or sale. Call (833)-248-4565 for guidance.
By Gabriel Shaw
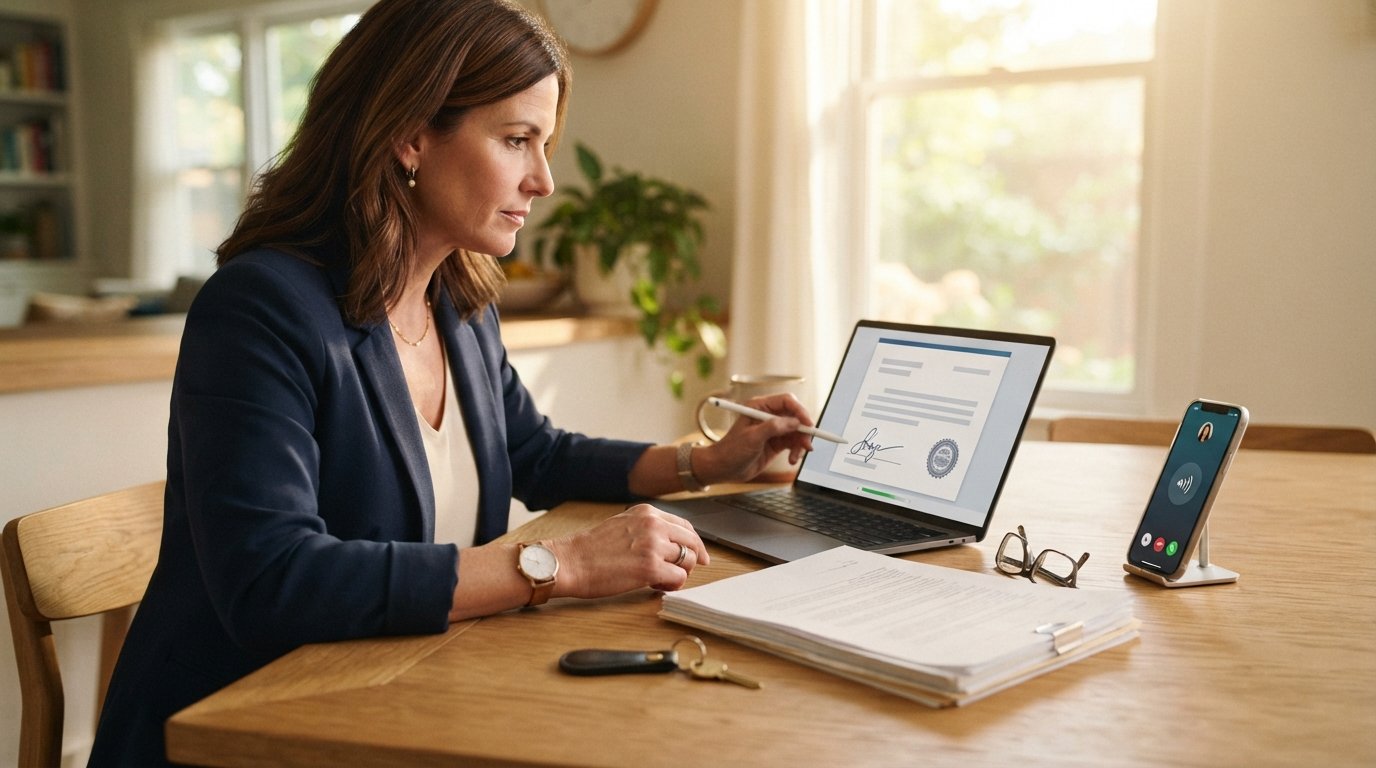
Your closing date is set, the moving truck is booked, and your lender just emailed a link to sign your final documents online. Remote online notarization (RON) has made it possible to complete a real estate closing from your kitchen table, but convenience comes with a catch: you are still legally bound by every page you sign. Once you click that final signature, reversing a mistake can cost thousands of dollars, delay your move, or even leave you owning a property with a clouded title. Before you trade a pen for a mouse, you need to ask the right legal questions. This guide walks you through the critical questions buyers and sellers should raise before an online real estate closing, with practical context on remote notarization, document review, title issues, and when to bring a real estate attorney into the conversation.
What Remote Online Notarization Changes and What It Does Not
Remote online notarization allows a notary public to witness signatures over a live audio-video feed, verify your identity through knowledge-based authentication or credential analysis, and apply a digital seal. Most states have adopted some form of RON, though the specific rules vary widely. Some states require the notary to be physically located in the same state as the signer, while others allow out-of-state notaries who are registered with the state. Before your closing, ask your closing agent or attorney a direct question: is the notary platform compliant with the laws of the state where the property is located? A closing that uses an unapproved platform can create recording problems and title defects that surface months or years later.
What RON does not change is the legal weight of the documents. A deed signed online transfers the same ownership interest as a deed signed at a physical table. A promissory note signed remotely carries the same repayment obligation. A settlement statement signed through a digital platform confirms your agreement to every fee listed. The convenience of the process can create a false sense of informality, but the legal consequences are identical. Ask your closing team to confirm that the electronic signatures and notarizations will be accepted by the county recorder and the lender. In some rural counties, recording offices still have limited capacity for electronic documents, and a rejected recording can stall your closing indefinitely.
Another key question: what happens if the technology fails mid-signing? Ask about the platform's contingency plan. If your internet drops during the notarization session, can the session be resumed, or must it restart from the beginning? Are there backup authentication methods if the knowledge-based authentication questions fail? These practical questions may seem minor, but a failed closing session can push your closing date back by days or weeks, especially if the seller's schedule or your rate lock expiration is tight. A reputable closing team will have clear answers and a written backup plan.
Documents to Read Closely: Disclosures, Deeds, and Settlement Statements
Online closings often deliver a large PDF package for review shortly before the signing session. The volume of paperwork can be overwhelming, but a few documents deserve close attention. Start with the seller's disclosures if you are the buyer. These forms list known defects, past repairs, water damage, permit issues, and other material facts about the property. In a digital closing, it is easy to scroll past these documents and click through to the signature pages. Ask your agent or attorney to point out any disclosures that seem incomplete or inconsistent with the inspection report. If a disclosure mentions a roof repair that the inspector did not note, or if the seller checked "no known issues" on a form while the inspection found active termite damage, you need to resolve those discrepancies before signing.
The deed is the document that actually transfers ownership, and it deserves a careful read. Check the legal description of the property, the names of the grantees (including how you want to hold title, such as joint tenants with right of survivorship or tenants in common), and the vesting language. A typo in a name or a missing middle initial can create title issues that require a correction deed later. Ask your closing agent to confirm that the deed matches the title commitment and the purchase contract. For sellers, the deed confirms that you are transferring the property free of liens and encumbrances, so verify that any existing mortgages or judgments are being paid off at closing and released of record.
The settlement statement, often called the Closing Disclosure, is the financial summary of the entire transaction. It lists every credit, charge, and proration. In a digital closing, review each line item against your loan estimate and your contract. Ask about any fee you do not recognize, any charge that increased from the original estimate beyond the allowed tolerance, and any seller credit that is not reflected correctly. A common mistake in online closings is accepting a settlement statement that includes a fee for a service you did not receive or a prorated tax amount that does not match the county records. Your closing agent should be able to explain every line, and you should not sign until you understand the numbers.
Finally, read the affidavits and certifications. These documents often include sworn statements about your occupancy, your citizenship status, or your knowledge of the property. Signing an affidavit that contains inaccurate information can expose you to legal liability. If you are unsure about a statement, ask before signing. The convenience of an online closing should never become a reason to skip the review process.
Title and Escrow Issues That Can Surface Late in a Digital Closing
Title problems are the silent deal killers of real estate transactions. In a traditional closing, the title company has weeks to research the chain of ownership, identify liens, and clear any defects. In a digital closing, the same process happens, but the compressed timeline and remote communication can make it easier for issues to slip through. Ask your closing agent for a copy of the title commitment and the underlying title search. Verify that the seller is the legal owner, that all mortgages and judgments are identified, and that any easements or restrictions are disclosed. If the property has been in the same family for generations, ask about heirs and estate issues. A missing heir or an improperly probated estate can create a title defect that requires a quiet title action, which can take months to resolve.
Escrow issues can also surface late. In a remote closing, the escrow agent holds funds and documents until all conditions are met. Ask how the escrow agent will confirm that the seller's existing mortgage is paid off and released. If the payoff statement is delayed or the lender does not send a release promptly, the buyer's title insurance may exclude coverage for that mortgage. Ask whether the title insurance policy will include a full release of prior liens and whether the underwriter will issue a clean policy at closing. If the answer is vague, get it in writing before you sign.
Another late-breaking issue is the survey. In many online closings, the survey is ordered early and reviewed remotely. If the survey shows a fence encroachment, a missing easement, or a boundary dispute, you need to resolve it before closing. Ask your attorney whether the survey exception in the title policy can be removed or whether you are accepting title with a known survey issue. If you are the seller, ask whether any encroachments have been addressed in prior transactions. A digital closing does not eliminate the need for a physical inspection of the property and a professional review of the survey.
Wire fraud is another critical concern in remote closings. Online transactions create opportunities for hackers to intercept email communications and send fraudulent wire instructions. Ask your closing agent about their wire verification procedures. Confirm that you will receive wire instructions through a verified, secure method, and never rely solely on an email. If you receive a last-minute change to wire instructions, call the closing agent directly using a phone number you have independently verified. A single fraudulent wire transfer can drain your down payment, and recovery is often impossible.
When to Involve a Real Estate Attorney Before Signing
Not every online closing requires an attorney, but many do. The answer depends on your state's laws, the complexity of the transaction, and your comfort level with the documents. In some states, attorneys are required to conduct closings; in others, title companies or escrow agents handle the process. If you are buying a property with a complicated title history, an unusual financing structure, or a seller who is an estate or a corporation, an attorney review is strongly advisable. If you are selling a property with multiple liens, a pending divorce, or a boundary dispute, an attorney can help you avoid signing a deed that creates future liability.
Ask yourself a few threshold questions. Do you understand every document in the closing package? If not, an attorney can explain them. Are there any disclosures that concern you? An attorney can help you evaluate whether you have a claim or a negotiation point. Is the title commitment clean, or are there exceptions that worry you? An attorney can review the title and advise you on the risks. If you are buying with a partner or spouse and want to hold title in a specific way, an attorney can draft the vesting language correctly. If you are a seller and the buyer has requested repairs or credits, an attorney can review the settlement statement to ensure the terms match the contract.
Even if you do not hire an attorney for the entire closing, a limited-scope review can be valuable. You can ask an attorney to review the settlement statement and the deed only, or to attend the closing session remotely. Many real estate attorneys offer flat-fee reviews for online closings. If you are unsure where to start, you can request quotes from local real estate attorneys with no obligation to hire. A directory service can connect you with attorneys in your area who handle residential closings and remote notarization issues. When you contact an attorney, ask about their experience with online closings and their fees for a document review. This step can save you from costly mistakes.
If you are working with a real estate agent, ask whether they have a list of attorneys who are familiar with digital closings. If you are working with a lender, ask whether the lender requires attorney involvement in your state. And if you are using a title company, ask whether they have an in-house attorney who can answer legal questions. Remember that the closing agent represents the transaction, not you personally. If you want independent legal advice, you need your own attorney. For general guidance on how to prepare for that first meeting, see our guide on questions to ask a lawyer at your first consultation, which covers how to evaluate an attorney's experience and fee structure.
Requesting Quotes from Local Real Estate Attorneys with No Obligation to Hire
If you decide to consult an attorney before your online closing, the next step is finding the right one. You can search for real estate attorneys in your city through a lawyer directory and request a quote. A reputable directory allows you to describe your situation, such as a remote closing with a title issue or a document review request, and receive responses from participating attorneys. There is no obligation to hire, and you can compare fees and experience before making a decision. When you request a quote, be specific about your needs: mention that the closing is online, that you want a review of the settlement statement and deed, and that you need the review completed before your signing date. This helps attorneys provide accurate quotes and timelines.
Before you choose an attorney, ask about their experience with remote online notarization and digital closings. Ask whether they have reviewed documents for your specific lender or title company before. Ask about their availability for a remote consultation and their turnaround time for document review. And ask about their fees: some attorneys charge a flat fee for a closing review, while others charge hourly. Get the fee structure in writing before you engage. You can also use a directory like TheLawyerDirectory to find attorneys in your area and request quotes. The directory is a U.S. lawyer-directory and advertising site, not a law firm and not a lawyer referral service. Participating attorneys may contact you, and there is no obligation to hire. This makes it a low-pressure way to gather information and compare options.
Once you have quotes, compare them on experience, responsiveness, and clarity. An attorney who answers your questions promptly and explains the process clearly is likely a better fit than one who offers the lowest fee but seems rushed. Remember that the cheapest review is not always the best value if it misses a critical issue. A thorough review of your closing documents can prevent a mistake that costs far more than the attorney's fee. And if you are selling, an attorney can help you understand your obligations under the purchase contract and ensure that the online closing process protects your interests.
Finally, keep in mind that an online closing is still a legal transaction. The convenience of signing from home should not lead you to skip the questions you would ask at a traditional closing table. Ask about the notary platform, the documents, the title, the escrow, and the wire instructions. Ask when to involve an attorney. And ask for quotes from local attorneys who can help you review the paperwork. With the right questions, you can approach your online closing with confidence and avoid surprises.