
Identity Theft and Fraudulent Credit Report Accounts: Steps to Take
Identity theft can create fraudulent credit report accounts. Learn steps to dispute errors and when to consult an attorney. Call (833)-248-4565 for help.
By Sophia Grant
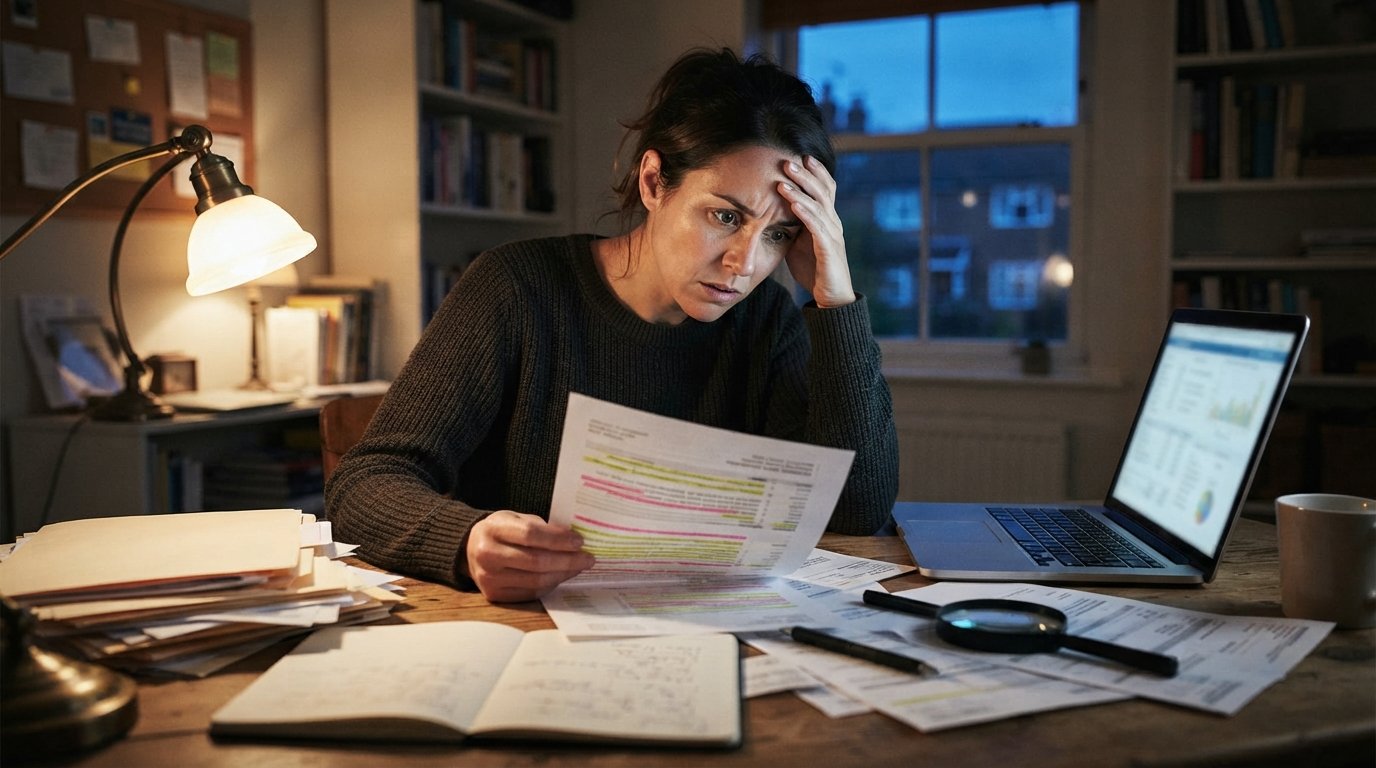
You pull your credit report to apply for a loan, and there it is: a credit card you never opened, a car loan you never signed, or a collection account for a store you have never visited. Your heart races. You wonder if you will be denied the mortgage, the apartment, or the job because of debts someone else created in your name. Identity theft that creates fraudulent credit report accounts is one of the most stressful forms of financial fraud because it attacks your reputation and your future borrowing power at the same time. The good news is that you have specific rights, a defined dispute process, and legal options if the system fails you. This guide walks you through what to do if identity theft creates fraudulent credit report accounts, from the first moment you spot the problem to the point where you may need to consult a consumer protection attorney.
How Fraudulent Accounts End Up on Your Credit Report
Fraudsters open new accounts using stolen personal information such as your Social Security number, date of birth, and address. They may apply for credit cards, personal loans, auto loans, or even utility accounts. Because the application uses your identity, the creditor reports the account to the credit bureaus under your name. The fraudster runs up charges or defaults, and the negative information lands on your credit file. Sometimes the fraud is obvious, like a maxed-out card from a retailer you never use. Other times it is subtle, like a small collection account that appears months later.
Fraudulent accounts can also appear through a process called synthetic identity theft, where a criminal combines real information (like your Social Security number) with fake details (like a different name or address) to create a new identity. That new identity may eventually be linked to your credit file, causing confusing errors. In other cases, a family member or someone you know may open an account in your name, which is still identity theft even if you know the person.
Early detection is critical. The longer a fraudulent account stays on your report, the more damage it can do and the harder it can be to untangle. You should check your credit reports regularly, ideally every few months, and review them line by line. Look for accounts you do not recognize, inquiries you did not authorize, and addresses or employers that are not yours. Many credit card issuers and banks offer free credit monitoring, and you can also get free reports from the major credit bureaus. If you spot something suspicious, act immediately.
First Steps: Document, Notify, and Freeze
When you discover a fraudulent account, your first instinct may be to panic or to call the creditor and demand answers. Instead, take a breath and follow a structured approach. Your goal is to create a clear record of the fraud, limit further damage, and start the formal dispute process. The steps below will help you regain control.
Begin by gathering evidence. Print or save a copy of your credit report with the fraudulent account highlighted. Write down the account number, the creditor name, the date opened, the balance, and any other details. Keep a log of every phone call, letter, and email, including dates, names, and what was discussed. This documentation will be essential when you dispute the account and, if necessary, when you speak with an attorney.
Next, notify the creditor that the account is fraudulent. Call the creditor's fraud department and follow up in writing. Ask them to close the account and to send you a letter confirming that you are not responsible for the debt. At the same time, file an identity theft report with the Federal Trade Commission (FTC) at IdentityTheft.gov. This report creates an official record and provides you with a recovery plan. You may also need to file a police report, especially if the creditor or a credit bureau asks for one.
Then, place a fraud alert or credit freeze on your credit files. A fraud alert tells creditors to take extra steps to verify your identity before opening new accounts. A credit freeze, which is free, restricts access to your credit report and makes it harder for thieves to open new accounts. You can request these through the major credit bureaus. A freeze is generally the stronger protection, but you will need to lift it temporarily when you apply for credit yourself.
- Document everything: Keep copies of credit reports, correspondence, and a written log of all communications.
- File an FTC identity theft report: Use IdentityTheft.gov to create an official record and get a recovery plan.
- Notify the creditor in writing: Ask for a fraud determination and a letter confirming you are not responsible.
- Place a credit freeze or fraud alert: Contact the major credit bureaus to restrict access to your credit file.
These initial steps are not just about cleaning up the current mess; they also help prevent new fraudulent accounts from appearing. Once you have a freeze or alert in place, you can move on to disputing the inaccurate information with the credit bureaus.
Disputing Fraudulent Accounts with the Credit Bureaus
Under the Fair Credit Reporting Act (FCRA), you have the right to dispute inaccurate or incomplete information on your credit report. When you dispute a fraudulent account, the credit bureau must investigate, usually within 30 days, and correct or remove information that is found to be inaccurate or unverifiable. The process is free, but it requires persistence and clear communication.
Start by obtaining your credit reports from all three major bureaus: Equifax, Experian, and TransUnion. You can get free reports from AnnualCreditReport.com. Identify each fraudulent account and prepare a dispute letter for each bureau. Your letter should clearly state that the account is fraudulent, provide the account number, and explain why it is inaccurate. Include copies (not originals) of your FTC identity theft report, police report (if you have one), and any correspondence with the creditor. Keep the letter concise and factual.
You can send dispute letters by mail with return receipt requested, or you can file disputes online through the bureaus' websites. Online disputes can be faster, but some consumers prefer mail because it creates a paper trail. After the bureau receives your dispute, it will contact the creditor. If the creditor cannot verify the account or agrees that it is fraudulent, the bureau must remove it from your report. If the investigation does not resolve the issue, you can ask the bureau to add a statement of dispute to your file, and you can file a complaint with the Consumer Financial Protection Bureau (CFPB) or your state attorney general.
Remember that disputing with the credit bureaus is only one part of the process. You should also dispute directly with the creditor, because the creditor is the source of the information. If the creditor agrees that the account is fraudulent, it should stop reporting it and may send a correction to the bureaus. Keep copies of all dispute letters and responses. If the bureaus or creditors fail to correct the error, you may need to escalate the matter.
When to Consult a Consumer Protection Attorney
Most fraudulent account disputes can be resolved through the steps above. However, there are situations where the system does not work as it should. If a credit bureau or creditor repeatedly fails to correct an error, or if you face collection efforts for a debt you do not owe, you may need legal help. Consumer protection attorneys specialize in credit reporting and identity theft cases and can help you enforce your rights under the FCRA and other laws.
You should consider consulting an attorney if you experience any of the following: a credit bureau refuses to investigate your dispute, a creditor continues to report a fraudulent account after you have provided proof, you are being sued or harassed by a collection agency for a fraudulent debt, or you have suffered significant financial harm (like being denied credit, housing, or employment) because of the error. An attorney can review your case, send demand letters, and, if necessary, file a lawsuit. The FCRA allows consumers to recover actual damages, statutory damages, and attorney fees in some cases, so legal representation may be more accessible than you think.
When you contact a consumer protection attorney, be prepared to provide a clear summary of the fraud and your efforts to resolve it. Bring your credit reports, dispute letters, responses from bureaus and creditors, and your identity theft report. The attorney will evaluate whether your rights have been violated and explain your options. Keep in mind that not every dispute requires a lawyer, but a consultation can help you understand whether you have a claim worth pursuing.
If you are looking for an attorney to help with credit report errors or identity theft, you can start by searching a reputable lawyer directory. TheLawyerDirectory is a U.S. lawyer-directory and advertising site, not a law firm and not a lawyer referral service. People use it to find lawyers in their city and request a quote; participating attorneys may contact them, and there is no obligation to hire. This can be a convenient way to connect with consumer protection lawyers who handle credit reporting issues in your area.
Documents to Gather Before Requesting a Legal Quote
When you reach out to a consumer protection attorney through a directory or directly, having the right documents ready can make the initial consultation more productive. Attorneys need to see the evidence of the fraud and the steps you have already taken. Without these documents, they may not be able to assess your case or provide meaningful advice.
Start with your credit reports from all three bureaus, with the fraudulent accounts highlighted. Include any dispute confirmation numbers or letters you sent to the bureaus. Gather correspondence with creditors, including letters you sent and responses you received. If you filed an FTC identity theft report, include that. A police report, if you filed one, is also important. Create a timeline of events: when you discovered the fraud, what you did, and who you contacted. This timeline will help the attorney understand the sequence of events and identify any delays or failures by the bureaus or creditors.
Also, be ready to explain any financial harm you have suffered. For example, were you denied a loan, an apartment, or a job because of the fraudulent account? Did you have to pay higher interest rates? Did you incur costs to resolve the fraud, such as postage or attorney fees? These details can affect the strength of your case. Having a clear, organized file will demonstrate that you have been diligent and will help the attorney evaluate your situation quickly.
What No Obligation to Hire Means When Using a Directory
When you request a quote through an advertising-based lawyer directory, you are not hiring a lawyer at that moment. The directory connects you with participating attorneys who may contact you to discuss your case. There is no obligation to hire any of them, and you are free to speak with multiple attorneys before making a decision. This gives you the opportunity to compare experience, fees, and approach without pressure.
It is important to understand that the attorneys listed in a directory are advertisers. They pay to be listed, and the directory may receive payment from them. This can affect which attorneys appear and in what order, but it does not mean the directory endorses any particular attorney. You should always do your own research and ask questions about an attorney's experience with credit reporting and identity theft cases. A directory is a starting point, not a substitute for your own judgment.
When you request a quote, be prepared to provide basic information about your situation. The attorney will likely ask for a summary of the fraud, the documents you have, and what you hope to achieve. This initial conversation is an opportunity for you to ask about the attorney's fees, timeline, and strategy. There is no cost or obligation to request a quote, and you should never feel pressured to hire an attorney on the spot. Take your time and choose the attorney who best fits your needs.
Protecting Yourself from Future Identity Theft
Once you have resolved the fraudulent accounts, you should take steps to protect yourself from future incidents. Identity theft can happen more than once, especially if your personal information is still in the hands of criminals. A few proactive measures can reduce your risk.
Keep a credit freeze in place when you are not actively seeking credit. A freeze is free and prevents creditors from accessing your credit report, which makes it harder for thieves to open new accounts. You can lift the freeze temporarily when you need to apply for credit. Monitor your credit reports regularly, and consider setting up alerts through your bank or a credit monitoring service. Be cautious about sharing your Social Security number and other personal information, and shred documents that contain sensitive data. If you receive suspicious emails or phone calls asking for personal information, do not respond; contact the organization directly using a verified number.
If you discover new fraudulent accounts in the future, repeat the steps outlined in this guide: document, notify, freeze, and dispute. The process can be time-consuming, but it is effective. And if you encounter resistance from creditors or credit bureaus, do not hesitate to seek legal advice. Consumer protection laws are on your side, and an experienced attorney can help you enforce them.
Identity theft that creates fraudulent credit report accounts is a serious problem, but it is not unsolvable. By acting quickly, documenting everything, and using the dispute process, you can clear your name and restore your credit. And if you need legal help, a lawyer directory can connect you with consumer protection attorneys who understand the system and can advocate on your behalf.